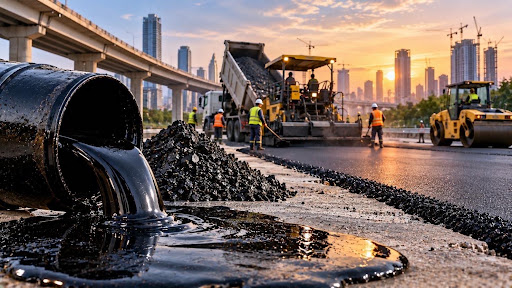
And the road surfacing budget is a subject that rarely makes front-page news. They should, to be perfectly frank, because they are the hidden hand of how cities develop. Now, a municipal planner designing a five-year paving program is drawing cost material assumptions from inputs that will likely be stale before the first construction season even wraps up. The bond between asphalt pavement, or bitumen which is a petroleum product, has been wound in a much tighter coil these past two years. Those gyrations do not remain limited to the trading floor. They show up in how transportation departments approach resurfacing, orchestrate bidding on highway work, and as procurement groups draft multi-year supply contracts.
Bitumen Price Trend is not Really a commodities tale for the urban planners, GIS experts or infrastructure economists. More of a window into how physical infrastructure systems respond as global supply has been squeezed after all.
How Bitumen Contributes to Road Construction
Bitumen alone does not do anything much. But sprinkle in aggregate, and you have asphalt concrete — the paving material beneath most of the worlds paved roads, city streets and highways. Its role is adhesive, to combine stone and sand into a substance that surrenders to the crushing of traffic rather than splitting apart. And that’s about as far as it goes to explain why asphalt remains the go-to material for everything from quiet neighbourhood byways to interstate highways. Which is also why bitumen supply and pricing is largely upstream from just about every resurfacing program any city or state runs. Agencies building out multiple years of pavement are taking a long-range bet on the availability and price of binder, even if they would never describe it that way.
What Drives the Bitumen Price Trend?
Crude Oil and Refinery Economics
It is the heaviest remaining fraction of crude oil after gasoline, diesel and jet fuel have all been distilled off. Its pricing, therefore, closely follows crude but never matches it move for move. There are refinery output decisions, seasonal demand, regional supply constraints; all layers on top of the base feed cost. Refinery utilization rates can matter more than we expect too since bitumen is also often a low-margin byproduct. Bitumen supply sits tight with crude at a standstill as refiners opt for higher-value fuels.
Geopolitical and Freight Factors
Geopolitics has been a true pull factor in recent days. As highlighted by supply chain analysis from Procurement Resource, Iran is among the largest bitumen exporters in terms of volume globally and this has resulted in market dynamics founded on the Iran-U.S. disruption of Iranian production and export logistics by the U.S.-Israel conflict in earlier 2025. Price moved: drum-packed bitumen surged from about $380 to $395 per metric tonne in that first quarter alone. Freight is another layer, with bitumen usually also travelling in a tanker or heated container, so any disruption to regional shipping lanes contributes cost which only manifests once the material hits land and not back at the refinery gate. For the seasonal part, paving demand in temperate climates has its own cycle that adds a short-term noise component to everything else.
Regional Market Differences
Bitumen markets don’t move together. For anyone conducting any comparative infrastructure research, that matters. Petronaft’s own market updates show that tracking prices in Northeast Asia and Europe have recently been quite similar, per tonne coming in around $540/month (Oct 2023), while North America has delivered sometimes over $640 or even higher. It’s due to refinery capacity, import dependence, domestic demand, not some one global price that we all pay. Another class of supply is natural bitumen and asphalt (not derived from refineries) which likewise shows geographic concentration. Canada, Venezuela and Kazakhstan had the highest production levels in 2024. Areas with less domestic refining capacity for heavy crude, or that depend on a small number of exporters, often experience sharper spikes when supply issues arise with any one supplier.
Bitumen Prices and Urban Planning
The bitumen volatility, for a transportation department, directly converts to budget uncertainty. The other thing is that resurfacing programs are planned years in advance, with unit costs per lane-mile being estimated long before a contract has even been let. Agencies either eat those price ups and downs out of contingency funds or they push components of the schedule back, and that reduction ultimately works its way into road condition indices and long-term maintenance costs when binder prices swing 10 or 15 percent over a single construction season. To manage this, procurement teams have begun building price-adjustment clauses into paving contracts so that payment terms are tied to published bitumen indices rather than locking a price in at bid time. Simply by watching both the bitumen market and how much construction activity is taking place around a city, planners now have an empowered way of actually knowing where to prioritize resurfacing jobs first as opposed to waiting yet another cycle in which they don’t get done.
Bitumen, GIS and Infrastructure Planning
Geographic information systems provide an additional tool for researchers to conceptualize bitumen supply chains spatially, rather than only as a line on a price graph. Asphalt plants, refineries, ports and storage terminals located in relation to the road network of a region allow estimating transportation distances and marking regions where logistics costs are most impacting delivered prices of materials.
Mapping Regional Supply Risk
This is not the only example of how a GIS-based approach can expose regional supply risk. Regions that rely on one port or just a couple of refineries for their bitumen are clearly much more vulnerable than anywhere with a variety of options serving the area. All of this does not require a specifically published case study to logically support it. It uses the same logic that has already been used in freight and logistics research, applied here to a true construction material with real budget implications for public agencies.
Environmental Impact and Asphalt Recycling
Role of Reclaimed Asphalt Pavement (RAP)
RAP (Reclaimed Asphalt Pavement) is at the core of how paving industry balances cost and environmental impact together. The Federal Highway Administration’s policy on the use of recycled materials, which prioritizes a cost-effective, environmentally responsible use of previously recycled pavement as long as it performs at least comparably to pavement made wholly from virgin materials. The association, along with data released last week by the National Asphalt Pavement Association (NAPA) and FHWA, estimated the industry reused 101.4 million tons of RAP in the fall 2024 construction season (and that using only virgin materials would have cost taxpayers an additional $4.7 billion). A high-RAP mix, according to FHWA, is one with more than 25 percent reclaimed binder content, and research published in a variety of industry journals has documented successful performance in mixes around the 30-to-50-percent range when properly engineered.
Challenges of High-RAP Mixes
This is RAP not an automatic win on cost or emissions in every project, however. Over time, a reclaimed binder hardens and becomes stiff. However, cramming high percentages of RAP in a mix can actually be detrimental to performance if done incorrectly with lack of design work or the use of rejuvenators. That’s because all those elements, whether it be engineering requirements, local specifications or the actual condition of the reclaimed material itself, determine if a given RAP mix is actually providing savings or just transferring that risk to another point in the pavement’s service life.
Tracking Bitumen Prices: A Market Research Strategy
On its own, one single bitumen price quote doesn’t say much to a researcher. Rather, a broader monitoring perspective considers crude oil benchmarks, refinery utilization, freight and tanker rates, regional construction activity, infrastructure spending plans and RAP supply simultaneously — because any one of these can move independently and still affect delivered cost paving material. Import and export volumes are also important, especially in regions that rely on only a handful of providing states.
If the bitumen price trend is thought of as one data point among many rather than a stand-alone number, then infrastructure researchers get much more solid ground on which to make predictions and plan budgets.
Key Factors to Monitor
- Crude oil benchmarks
- Refinery utilization
- Freight and tanker rates
- Regional construction activity
- Infrastructure spending plans
- RAP supply
- Import and export volumes
- Regional supplier concentration
- Conclusion
- Bitumen occupies a weird nexus of energy markets, transportation planning and environmental policy. It’s not a commodity, so treating it that way misses most of what makes studying it worth the effort. Whether urban planners tracking paving budgets, GIS analysts mapping supply chain exposure or procurement teams managing contract risk, all contend with the same underlying unknowns — from different angles. As infrastructure agencies attempt to stretch increasingly limited budgets across increasingly aging road networks, lending better spatial and data-driven models surrounding the availability of bitumen supply,and pure education of the global trend point education recycled material availability and regional price behaviour will only matter more.
also read this – https://globaltrendpoint.com/write-for-us/